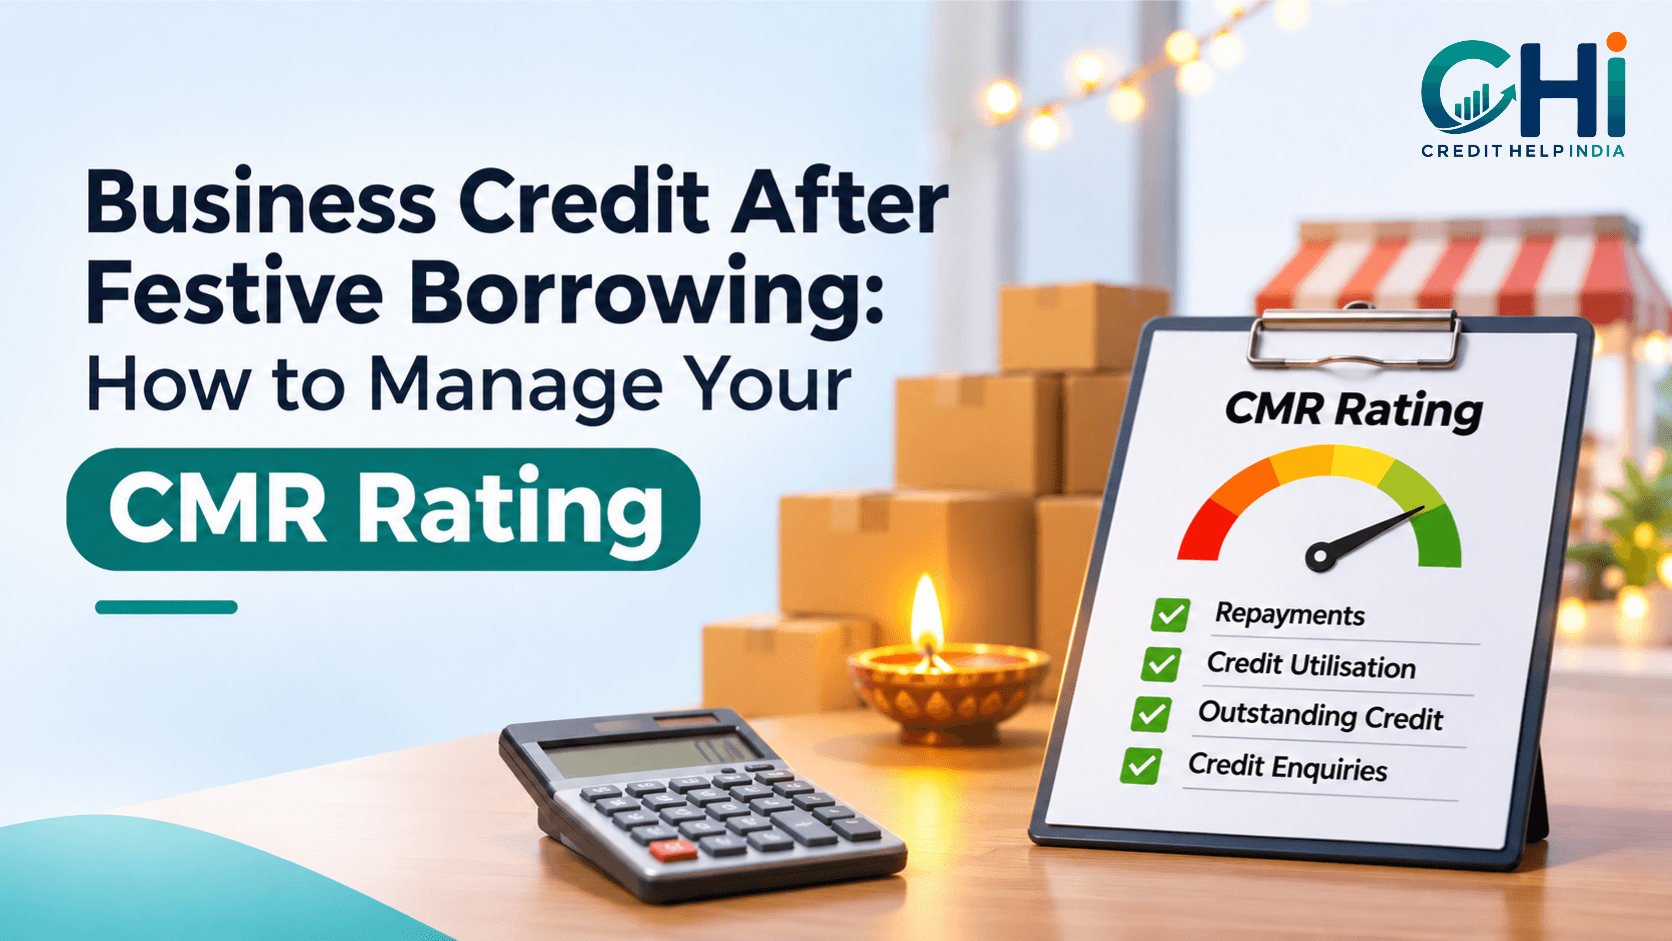
Business Credit After Festive Borrowing: How to Manage Your CMR Rating
For many MSMEs, the festive season brings higher demand but also higher working-capital requirements. A 2026 MSME survey found that 66% of businesses anticipated additional funding requirements for the festive season, while 55% planned to increase inventory.
Borrowing to manage this demand does not automatically hurt your CMR rating. What matters is how the business manages its credit after borrowing, particularly repayment behaviour and credit utilisation.
The CIBIL Rank is derived from a company's Company Credit Report (CCR) and is provided on a scale from 10 to 1, with 1 being the best rank. CIBIL states that past repayment behaviour and credit utilisation are major parameters used to calculate the rank.
Why Do MSMEs Borrow More During the Festive Season?
Festive demand can require businesses to spend before they receive the resulting revenue.
A retailer may need to purchase additional inventory. A manufacturer may need more raw materials. A wholesaler may need to increase stock to fulfil larger orders. This creates a temporary working-capital requirement.
For some businesses, internal cash reserves may be sufficient. Others may use working-capital facilities, business loans or other forms of credit.
The important consideration is whether the additional borrowing is aligned with expected cash flow and the business's ability to repay it.
Does Festive Borrowing Affect Your CMR Rating?
Festive borrowing itself does not automatically reduce your CMR rating.
CMR, or CIBIL Rank, reflects information contained in the company's credit history. CIBIL identifies past repayment behaviour and credit utilisation as major parameters used in calculating the rank.
This means a business can take additional credit during a high-demand period without assuming that the borrowing alone will damage its business credit profile.
The concern arises when additional borrowing is accompanied by delayed repayments, high credit utilisation or unnecessary new credit applications.
How Does Credit Utilisation Affect Your CMR?
Credit utilisation reflects how much of the available credit a business is using.
For example, consider an MSME with a ₹50 lakh working-capital limit. If it regularly uses ₹45 lakh, its outstanding utilisation is significantly higher than if it uses ₹20 lakh.
CIBIL identifies credit utilisation as one of the major parameters used to calculate CIBIL Rank.
After the festive season, businesses should therefore review whether the additional working-capital requirement has reduced as expected.
If inventory has been converted into sales and receivables are being collected, the business may be able to reduce outstanding utilisation. If sales have not materialised as expected, the business may need to reassess its repayment and cash-flow position.
Why Is Repayment Discipline Important After Festive Borrowing?
Festive borrowing often happens before the revenue it is intended to support. That makes the post-festive period particularly important.
Businesses should review upcoming:
- Loan repayments
- Working-capital obligations
- Interest payments
- Supplier dues
- Other scheduled credit commitments
A business may have strong sales on paper but still experience cash-flow pressure if receivables are delayed or inventory takes longer to convert into cash.
Since repayment behaviour is a major component of CIBIL Rank, businesses should prioritise timely repayments even after the festive demand period has ended.
Can Multiple Business Loan Applications Affect Your Credit Profile?
They can create multiple credit enquiries.
When a business approaches lenders for credit, the lender may access its company credit report. The report provides lenders with information about the company's credit history and helps them make credit decisions.
This is particularly relevant if a business takes one loan during the festive season and then immediately starts applying to several other lenders for additional funding.
The better approach is to first establish the actual funding requirement, assess repayment capacity and compare appropriate financing options before submitting multiple applications.
What Should an MSME Do After the Festive Season?
A post-festive credit review can help a business understand whether its borrowing remains manageable.
Review outstanding credit.
List all active loans, working-capital facilities, and other business credit. Look at the outstanding amount and available limits.
Check repayment schedules
Review upcoming EMIs, interest payments and other credit obligations against expected cash inflows.
Monitor credit utilisation
Assess whether borrowing remains high even after the temporary festive requirement has passed.
Avoid unnecessary new borrowing
If the original borrowing has not yet been absorbed through business cash flow, taking additional credit may increase financial pressure.
Review the business credit report
A Company Credit Report provides a record of the company's credit payment history and helps lenders assess its credit profile.
Regular review can help businesses identify information that needs attention before applying for additional credit.
Should Your Business Take Another Loan After Festive Borrowing?
There is no universal answer.
A business should consider another loan only after assessing its actual funding requirement and repayment capacity.
If festive sales met expectations, the business should review whether existing borrowing can now be reduced. If sales were lower than expected, it may be more important to reassess cash flow before taking on additional credit.
Businesses should also consider whether inventory remains unsold or receivables are delayed. If the original borrowing has not yet translated into sufficient cash flow, another loan could increase financial pressure.
On the other hand, if additional working capital is genuinely required and the business can support the repayment obligations, it can compare suitable financing options before applying.
The objective should be to use business credit as a financial resource rather than allowing short-term borrowing to become a long-term cash-flow problem.
How Can MSMEs Maintain a Healthy CMR Rating?
Businesses can focus on a few fundamentals:
- Make repayments on time
- Monitor credit utilisation
- Keep track of outstanding borrowing
- Avoid unnecessary credit applications.
- Review the company credit report regularly
- Plan new borrowing around actual repayment capacity
A healthy business credit profile is built through consistent credit management rather than one-time actions.
FAQs
1. Does festive borrowing reduce the CMR rating?
Not automatically. Borrowing itself is not the only consideration. CIBIL identifies repayment behaviour and credit utilisation as major parameters in calculating CIBIL Rank.
2. What affects the CMR rating?
CMR, or CIBIL Rank, is derived from the company's credit report. Past repayment behaviour and credit utilisation are major parameters used in its calculation.
3. Does high credit utilisation affect business credit score?
Credit utilisation is an important factor in CIBIL Rank. Businesses should therefore monitor how much of their available credit they are using.
4. Can multiple business loan applications affect credit profiles?
Multiple loan applications can result in credit enquiries being recorded. Businesses should assess their funding requirements before submitting multiple applications.
5. How can an MSME maintain a healthy CMR rating?
Timely repayments, sensible credit utilisation, controlled borrowing and regular review of the Company Credit Report can help businesses manage their credit profile more effectively.
Frequently Asked Questions
CIBIL is a repository of information that collects and maintains the data provided by Banks and NBFCs, where individual have or had loans in the past. It has information about individual past and present repayment history and the status of individual loan accounts, personal information such as individual identity information, employment history, contact information, etc. It also keeps track of all the enquiries that individual has made for credit from various banks and financial institutions.
Get your credit fixed. Open doors to better
loans, cards, and rates.
Loan rejection, low score, no credit history or starting a new business we find what's wrong and fix it.